Artificial intelligence (AI) and the related datacenter buildout has been the predominant theme in capital markets over the past several years in our view, driving massive capital expenditures and powering certain large cap equities into mega-cap status. However, gaining exposure to AI datacenters in the fixed income market is not as straightforward as simply owning the Magnificent Seven (Mag-7). The fixed income market offers investors over $400B worth of options, ranging from corporate debt to club deals, to various flavors of securitized products. How investors choose to gain datacenter exposure can be as custom as toppings on an ice cream sundae. Let’s dig in.
Investment Grade Hyperscaler Corporate Debt:
- Frequent, multi-tranche corporate bond deals from Amazon, Google, Meta, Microsoft, Oracle, and SpaceX
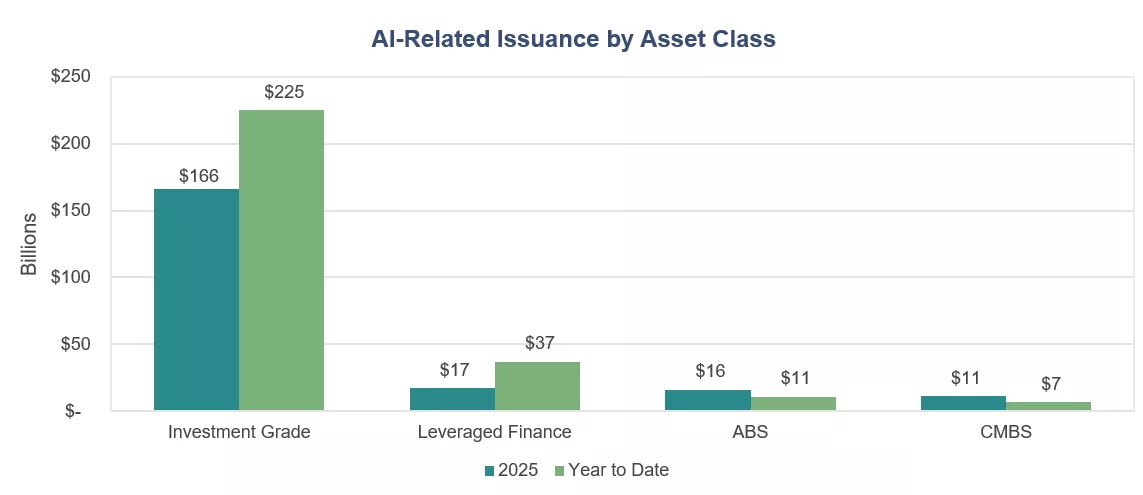
- Historically, hyperscalers have not been active issuers. That has changed. Hyperscaler issuance increased from $17B in 2024 to $121B in 2025. $182B has already been issued in 2026.
- Despite the rapid increase in debt issuance, credit quality has remained stable. Four of the six hyperscalers are rated AA or higher.
- Issuance has been across the curve in multiple currencies. Google was able to issue a 100-year bond in British Pound Sterling.
- Some issuers are also creatively issuing debt through special purpose vehicles (SPVs) that is ‘off balance sheet’. These deals tend to offer additional spread relative to what their ratings would otherwise suggest.
High Yield and Leveraged Loans
- Issuers are also using the SPV model to issue in the High Yield market.
- These are unique structures where the debt is issued out of a SPV and the hyperscaler provides various forms of credit enhancement and structural protection such as parent guarantees, funded reserve accounts, amortizations, etc.
- These deals are effectively a form of project finance, first lien AI infrastructure bonds backed by long-term hyperscaler cash flows, rather than traditional unsecured high yield bonds issued against a volatile operating business.
Asset-Backed Securities:
These securities are backed by the operating cash flows of the datacenter, primarily tenant lease receivables.
Collateral typically includes leases, physical infrastructure, and operating contracts, with a focus on the durability of the operating platform rather than pure property value.
- Datacenter asset-backed securities (ABS) tenant types are primarily segmented into hyperscaler and colocation. Hyperscalers include larger, more highly-rated technology companies, while colocation deals have multiple tenants of mixed credit profiles which may be more commercially oriented.
- Funding data centers in the ABS market began in earnest in 2020. As of YE 2025, datacenter ABS outstanding was $36.6B, which represented 4.6% of all ABS outstanding. The datacenter market share has doubled from 2.3% in 2023 as the sector has rapidly expanded.
- ABS data center issuance totaled $16B in 2025.
Commercial Mortgage-Backed Securities:
Secured by a mortgage on a specific property or campus, usually structured as a single-asset, single-borrow (SASB) loan.
The underlying data centers are typically stabilized, fully leased assets located in major demand hubs with strong power availability and supporting infrastructure.
Key considerations include:
- Newer facilities that are well positioned to benefit from growing AI-driven demand with potentially lower risk of technological obsolescence.
- Assets with long-term leases in place with high-quality, credit tenants, where lease terms extend close to or beyond loan maturity and tenants may be more likely to renew.
SASB commercial mortgage-backed securities (CMBS) datacenter issuance totaled $11B in 2025 and is expected to reach approximately $10B in 2026.
About the Author
Gregory Zage, CFA®, Executive Director, joined SCM in 2007 and has investment experience since 2007. Gregory is a Senior Fixed Income Portfolio Manager and Head of Fixed Income Trading. He is currently responsible for all trading activity across SCM's fixed income desks. Previously at SCM, he was responsible for high-grade corporate credit trading and municipal credit trading. Gregory received his B.A. in Economics with a minor in Spanish from Davidson College. He holds the Chartered Financial Analyst® designation.
Related Insights
11.12.2026 • Charles Wittmann, CFA®
10.29.2026 • Gregory Zage, CFA®
The Sterling Capital VAULT: An Update on FOMC Dissenting Votes: Warsh Edition
10.23.2026 • Peter Brown, CFA®
The Sterling Capital VAULT: The 2026 U.S. Midterm Elections & Fixed Income Market
10.13.2026 • Charles Wittmann, CFA®