Skip Navigation

The Lead - Lessons from 1978

10.13.2026

The Lead - Lessons from 1978

Tags: Equity, Economic Updates

Higher Yield, Lower Return: Dividend Stocks in 1978-79

Cumulative Total Return, January 1978-December 1979, as 10-year and Long Treasury Yields Rose
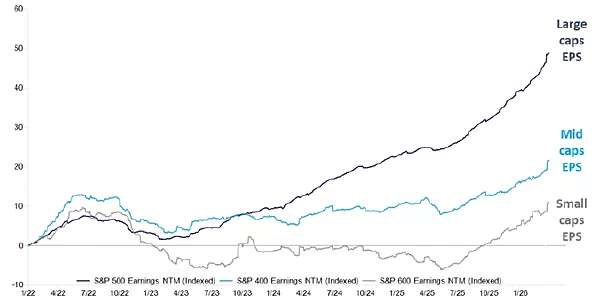
Our review of market history suggests the late 1970s was the most recent period in which both U.S. 10- and 30-year Treasury yields moved materially higher at the same time. Examining that timeframe further offers insight into dividend-paying stocks and sectors that outperformed as interest rates climbed.

We believe the main takeaway from that era is that  lower-yielding dividend payers outperformed relative to the higher yielders. From January 1978 through December 1979, the 30-year Treasury yield rose about two percentage points to 10%, and the 10-year yield rose about 2.5 points. Stocks posted positive returns, appearing to keep ahead of higher inflation over the two years, while posting single digit returns. Then, as now, rising oil prices and inflation worries seemed to push interest  rates higher. In the chart to the right, energy companies appeared to benefit from their ability to raise prices alongside inflation, whereas utilities, whose rates where regulated and revenues could not increase at the rate of inflation, generally underperformed. Among dividend-paying stocks, the lowest-yielding quintile returned 56% over the two years, compared with the 11% gain generated by the highest-yielding quintile.

One signal worth watching was whether short-term rates rose faster than long-term rates, a pattern known as a “bear flattener.” That dynamic appeared to weigh on financial stocks, in particular banks because their funding costs rose while returns on existing loans adjusted more slowly, putting pressure on profitability.
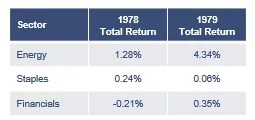
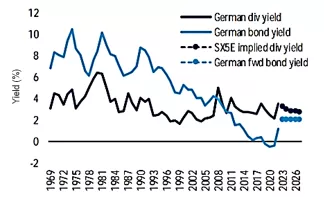
German Dividend Yields Climbed with Bond Yields in the Late 1970s

The pattern wasn’t limited to the U.S. In Germany, dividend yields climbed along with bond yields in the late 1970s, as seen in the chart above. Looking back over these years indicates that when bond yields rose, dividend yields rose too.

Should the current environment echo the late 1970s, we believe the most attractive opportunities may lie in dividend-paying companies capable of growing their revenues and cash flows, thus creating the potential for both higher stock prices and higher dividends over time.

As always thank you for your interest and trust managing your investments.


Disclosures

Past performance is not indicative of future results. Any type of investing involves risk and there are no guarantees that these methods will be successful. Economic charts are provided for illustrative purposes only. The information provided herein is subject to market conditions and is therefore expected to fluctuate.

The opinions contained in this presentation reflect those of Sterling Capital Management LLC (SCM), are for general information only, and are educational in nature. The opinions expressed are as of the date of publication and are subject to change without notice. These opinions are not meant to be predictions and do not constitute an offer of individual or personalized investment advice. They are not intended as an offer or solicitation with respect to the purchase or sale of any security. This information and these opinions are subject to change without notice. All opinions and information herein have been obtained or derived from sources believed to be reliable. SCM does not assume liability for any loss which may result from the reliance by any person upon such information or opinions.

Investment advisory services are available through SCM (CRD# 135405), an investment adviser registered with the U.S. Securities & Exchange Commission (SEC) and an indirect, wholly-owned subsidiary of Desjardins Global Asset Management Inc., which is part of the Desjardins Group. SEC registration does not imply a certain level of skill or training, nor an endorsement by the SEC. SCM manages customized investment portfolios, provides asset allocation analysis, and offers other investment-related services to affluent individuals and businesses.

Sterling Capital does not provide tax or legal advice. You should consult with your individual tax or legal professional before taking any action that may have tax or legal implications.

The securities described are neither a recommendation nor a solicitation. Security information is being obtained from resources the firm believes to be accurate, but no warrant is made as to the accuracy or completeness of the information.

The volatility of an index varies greatly. All indices are unmanaged and investments cannot be made directly in an index.

The S&P 500® Index is a stock market index weighted by market capitalization that is made up of 500 of the largest public companies in the U.S.

Technical Terms: The price-to-book (P/B) ratio is a financial metric that compares a company's market value to its book value, total assets minus total liabilities. Return on equity (ROE) is a financial performance ratio that measures how effectively a company uses shareholders’ equity to generate net income. It is calculated by dividing net income by average shareholders’ equity. A risk profile outlines an individual or organization's willingness and ability to take on financial risks, guiding their investment or operational strategies. (Technical definitions are sourced from Corporate Finance Institute and Investopedia.)

The Chartered Financial Analyst® (CFA) charter is a graduate-level investment credential awarded by the CFA Institute, the largest global association of investment professionals. To earn the CFA charter, candidates must: 1) pass three sequential exams; 2) have at least four thousand hours of qualified professional investment experience; 3) join CFA Institute as members; and 4) commit to abide by, and annually reaffirm, their adherence to the CFA Institute Code of Ethics and Standards of Professional Conduct.

Since we began publishing The Lead in 2015, our primary purpose has been to communicate our investment philosophy and process as an investment advisor in the context of changing markets. In creating portfolios that differ from our benchmarks by focusing on characteristics that have a long term history of attractive relative returns according to Ned Davis Research, the portfolios are different from the benchmarks and as a result there can be periods where results differ including below benchmark performance. Since strategies are oriented toward the long term characteristics, if those characteristics are out of favor over a period of time, the given strategy’s performance could be challenged in terms of relative performance. While Sterling believes active professional investment management that employs a consistent process with a long term orientation and aligned with client interests offers benefits, management fees to support the active approach can be higher than certain alternatives. When hiring an investment manager we believe it is important to monitor the investment risks taken including sector concentrations, portfolio turnover, and the impacts of dividend policy changes.

About the Author


Photo of Charles Wittmann

Charles Wittmann, CFA®

Co-Portfolio Manager

Charles Wittmann, CFA®, Executive Director, joined SCM in 2014 and has investment experience since 1995. Chip is Co-Portfolio Manager of the Equity Income strategy. Prior to joining SCM, he worked for Thompson Siegel & Walmsley as a portfolio manager and (generalist) analyst. Prior to TS&W, he was a founding portfolio manager and analyst with Shockoe Capital, an equity long/short hedge fund. Chip received his B.A. in Economics from Davidson College and his M.B.A. from Duke University's Fuqua School of Business. He holds the Chartered Financial Analyst® designation and served as President of CFA Society Virginia from 2012-2013.

Related Insights


09.11.2026 • Charles Wittmann, CFA®

The Lead - When Cheap May Be Risky

08.31.2026
James Kerin, CFA®, Gregory Zage, CFA®

The Sterling Capital VAULT: Return of the Term Premium

07.14.2026 • Charles Wittmann, CFA®

The Lead - Case for Compounding

Scroll Up